Home loans

Home Purchase Loans

Buying a home is one of the biggest investments you’ll make. We help you understand your budget, compare loan programs and move from pre-qualification to closing day with confidence.

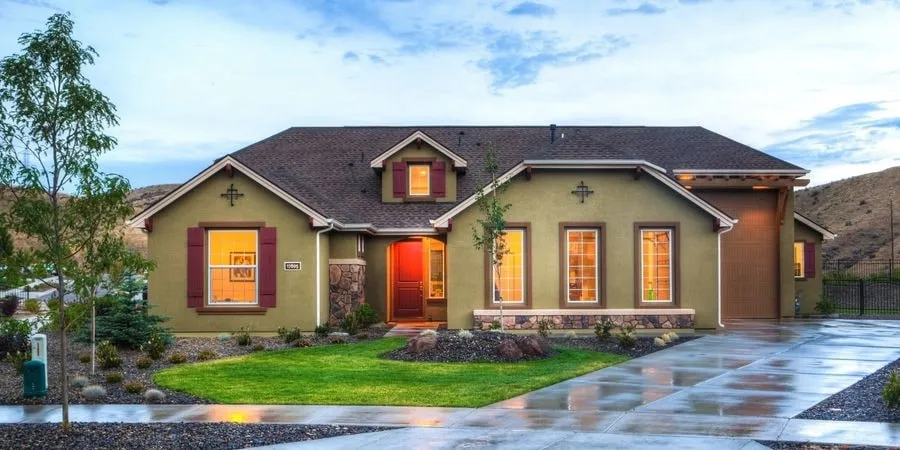
A two-story home with a stone walkway and a front lawn at dusk
  • Know your budget

    We review your income, assets and debts so you know what you can comfortably afford before you start shopping.

  • Shop with a pre-qualification

    Make offers backed by a pre-qualification letter that shows sellers you’re a serious buyer.

  • Programs compared for you

    Conventional, FHA, VA and jumbo options from a wide network of lenders, side by side.

  • One point of contact

    Your loan officer works with your agent and the title company all the way to closing.

Buying a home with Metro Mortgage

Purchasing a home isn’t only a dream — it’s probably one of the biggest investments you’ll make in your lifetime. Getting a home loan financed is a complex process, and it pays to be prepared before you take that step.

At Metro Mortgage LLC, an experienced mortgage advisor is always ready to answer your questions and walk you through the loan application. We’re with you at every step, until you open the door to your new home.

How buying with us works

  1. Talk to us about your goals. We review your income, assets, debts and credit, and explain the programs that fit.
  2. Get pre-qualified. Shop knowing your budget, with a letter you can include with your offers.
  3. Find your home and make an offer. We work with your real estate agent on timing and contract details.
  4. Apply and lock your rate. Complete your application through our secure online portal and lock your rate when the timing is right.
  5. Processing, appraisal and underwriting. We gather documents, order the appraisal and keep your file moving.
  6. Close and get your keys. You’ll review your Closing Disclosure before closing day, then sign and move in.

See the full mortgage process for what happens at each step.

Choosing the right loan

  • Conventional loans: fixed- or adjustable-rate financing for buyers with solid credit.
  • FHA loans: flexible credit guidelines and a low down payment, popular with first-time buyers.
  • VA loans: for eligible veterans, service members and surviving spouses, with no down payment for eligible borrowers.
  • Jumbo loans: for loan amounts above the conforming limit, common in Northern Virginia.

Buying for the first time? Our first-time home buyer guide covers assistance programs in Virginia, Maryland and DC.

FAQ

Home purchase: common questions

How much do I need for a down payment?

It depends on the loan program. VA loans offer options with no down payment for eligible borrowers, and FHA and some conventional programs allow a small down payment. Down payment assistance may also be available. We’ll compare your options based on your budget and savings.

Is pre-qualification the same as a loan approval?

No. Pre-qualification is an early review of your income, assets, debts and credit that estimates how much you may be able to borrow. Final approval comes after underwriting reviews your documents, the appraisal and the property.

What costs should I plan for besides the down payment?

Plan for closing costs (such as lender, appraisal, title and recording fees), prepaid items like property taxes and homeowners insurance, and moving expenses. Your Loan Estimate lists the expected costs for your loan.

Ready to talk about your home loan?

Get clear answers from a local team, with no pressure and no obligation.

Call Us Apply Now